
MCA Debt and Equipment Leases: Double Payment Trap
Equipment lease payments and MCA daily debits hit the same account. See how cross-defaults work and what options exist before one missed payment.
Two Payments, One Bank Account
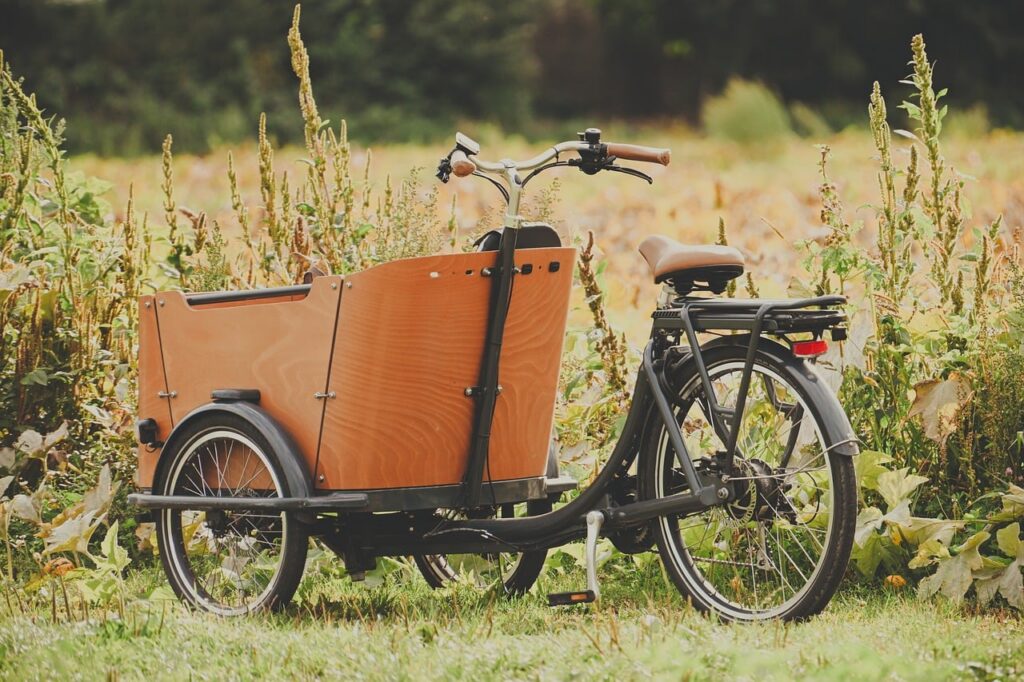
It is the middle of October and the lease payment on the delivery van hits on the first of the month. The daily debit from your merchant cash advance hits every morning at 6am. Between them, your operating account is being drawn from two directions, and neither creditor cares about the other.
That is the equipment lease squeeze. Trucks, ovens, dental chairs, salon stations, and CNC machines are often financed through leases, and a lot of owners who already carry those obligations end up taking an MCA to cover a slow month. The lease does not pause. The MCA does not pause. Both of them want to be paid first.
This article explains how equipment lease payments and MCA daily debits interact, what each creditor may be able to do, and what options exist before one missed payment turns into two defaults. It addresses commercial business debt only, and it is written for owners who would rather understand the mechanics now than learn them from a default notice.
How an Equipment Lease Actually Works
A true lease means the lessor owns the equipment and you pay to use it. A finance lease, or a lease with a one-dollar buyout, behaves more like a loan with the equipment as collateral. The label on the contract matters, because it changes who owns the machine and what happens when payments stop.
Commercial leases are governed largely by Article 2A of the Uniform Commercial Code, and you can read the model text through the Cornell Legal Information Institute. In general, the lessor can repossess the equipment after a default, and many leases also carry acceleration clauses that make the whole remaining balance due at once.
Most leases also include a cross-default clause. That language says a default on any other debt of the business can count as a default under the lease. An MCA default may therefore reach into your lease even if every lease payment was made on time, which is the part that surprises most owners.
Where the MCA Funder Comes In
An MCA is not a loan in the legal sense, and the contract is built around the purchase of future receivables. Many agreements still include a UCC-1 filing that describes the collateral broadly, often as all accounts, receivables, and sometimes equipment. If that filing names equipment, it can collide with the lessor’s own interest in the same machine.
The funder’s daily debit also comes straight out of the account the lessor draws from. When the daily debit takes the cash first, the lease payment bounces. When the lease payment is drawn first, the next MCA debit can bounce. Either bounce can trigger fees, default notices, and sometimes a call from both creditors in the same week.
Read your MCA agreement for the definition of receivables, any language about equipment or other collateral, and any covenant that restricts additional financing or leases. Some contracts prohibit new obligations without the funder’s consent, which can turn a routine lease renewal into a technical default before you even miss a payment.
The Math That Breaks the Month
Take a composite example. A landscaping company leases two mowers and a trailer for $2,100 a month, and its MCA debits $380 each business day. With about 21 debit days in a month, that is roughly $7,980. Together the two obligations take more than $10,000 before payroll, fuel, or insurance.
If monthly revenue is $38,000, those two payments alone eat more than a quarter of it. A slow week, a rainy stretch, or a late-paying customer, and the account runs dry in the third week. This is composite math, not a real client, and every business has different numbers.
The pattern is common because the cash drain is invisible until the account balance hits zero. The lease feels small, the daily debit feels small, and nobody adds them together until a payment fails. A simple monthly schedule that lists every fixed obligation by date often reveals the problem weeks earlier, while there is still time to act.
One practical habit helps here. Line up the dates on a single calendar, including the day each lease draft clears and the days your daily debit runs, then compare that against when your own customers typically pay you. If the biggest outflows land right before your biggest inflows, you have found the pressure point, and that is the exact detail worth raising with any creditor you approach.
What Each Creditor May Do After a Missed Payment
The lessor’s first step is usually a late fee and a notice. After that, the lessor may demand the full balance, repossess the equipment, and pursue any personal guarantee attached to the lease. If the equipment is critical to making money, losing it can end the business even if the MCA could have been resolved.
The MCA funder’s path often starts with calls and a default notice, and can move toward a lawsuit, bank account restraints, or a claim under a personal guarantee. For background on how these products are used, the Consumer Financial Protection Bureau publishes public research on small business lending.
The important point is that the two creditors move on different clocks. The lessor may be the faster one because repossession is comparatively simple. That is why the order in which you address them can change which options are still on the table.
Owners also tend to forget that a repossessed machine rarely ends the debt. If the equipment sells for less than the remaining lease balance, the lessor may pursue the difference, and the funder may still hold its claim. Losing the asset and keeping the liability is a common outcome, which is another reason to open the conversation early rather than late.
Options That Exist Before Default
Owners usually have more room than they think, especially early. A lessor may agree to defer a payment, restructure the term, or add a few months to the end of the lease. These requests tend to work best when they arrive before a payment is missed, with a clear plan attached.
On the MCA side, a hardship request, a revised payment schedule, or a negotiated resolution may lower the daily burden. Some funders also work through a forbearance arrangement that pauses or reduces debits for a set period. Creditors may not always agree to proposed terms, so the outcome depends on the contract, the funder, and the facts of the business.
Federal data also shows how common cash flow pressure is among small firms. The Federal Reserve Small Business Credit Survey publishes annual findings on financing needs and challenges. Reading it will not solve your case, but it shows you are not the only owner juggling these obligations.
What to Do Next
Start with a one page list of every fixed payment: each lease, each MCA debit, and each due date. Mark which equipment is essential to earning revenue, and which could be returned or swapped. Then pull out the lease and MCA agreements and read the cross-default, collateral, and additional financing sections.
After that, talk to people who handle this every day. An MCA Relief Specialist or MCA Options Specialist can walk through the debit schedule, the contract language, and the paths that exist, from a hardship request to a negotiated settlement. A business attorney can speak to how your state treats lease defaults and repossession.
You do not have to choose between keeping the equipment and keeping the funder at bay. There are real options, and most owners learn about them only after someone lays them out. This information addresses commercial business debt and is not consumer debt advice. Results vary and are not guaranteed. Past performance does not predict future results, and every situation is different.
Photo credits: Featured image by cornerstone accounting Services on Unsplash; Section 1 by Alexas_Fotos on Pixabay; Section 2 by Ceba Solutions on Unsplash; Section 3 by Zulfugar Karimov on Unsplash; Section 4 by Jakub Żerdzicki on Unsplash; Section 5 by Jacob McGowin on Unsplash; Section 6 by bruce mars on Unsplash; Section 7 by RDNE Stock project on Pexels.