
Gas Station MCA Debt: Thin Margins Meet Daily Debits
Fuel margins run 1-3%. A daily MCA debit doesn't care. Here's how gas station and convenience store owners get out of stacked advances.
When the Pump Price Moves and the Debit Doesn't
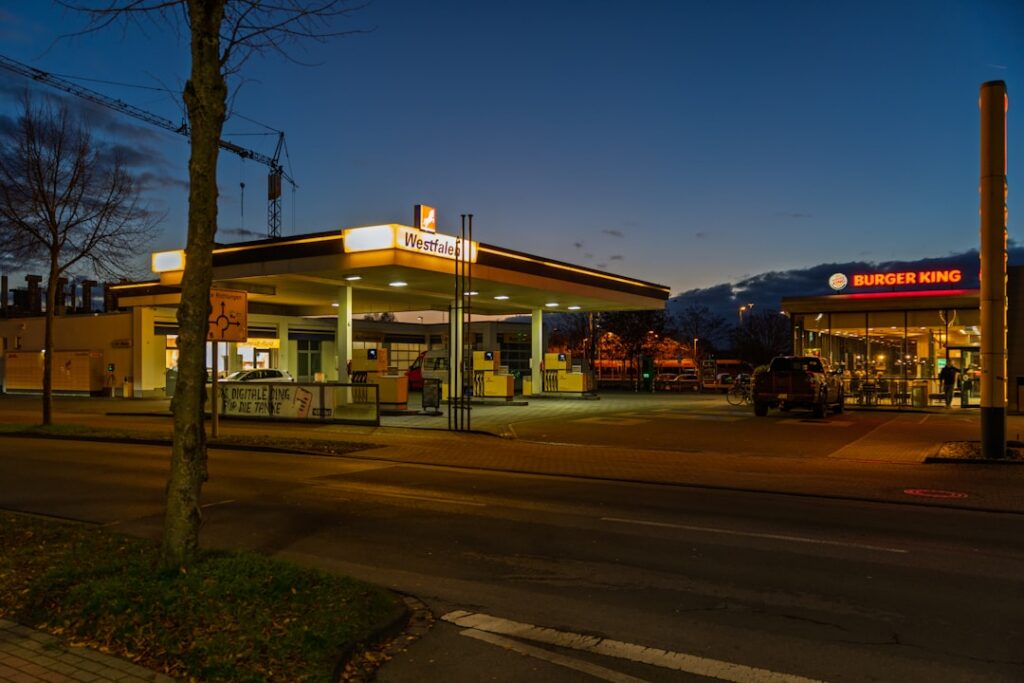
Run a gas station or convenience store and you already know the math nobody outside the industry believes: you can sell $18,000 of fuel in a day and clear maybe $300 of actual margin on it. Fuel is a pass-through business. The card networks take their cut, the distributor sets the wholesale price, and you’re left with pennies per gallon while carrying the full cost of the inventory on your books. The convenience store side, tobacco, lottery, snacks, coffee, is where the real margin usually lives.
Now put a merchant cash advance on top of that. An MCA doesn’t care that Tuesday was slow because a competitor two exits down dropped their price six cents. It doesn’t care that your card processor held a reserve for three days after a chargeback dispute. It pulls its fixed daily amount, rain or shine, gas price spike or gas price crash. For a business already operating on razor-thin fuel margins, that fixed daily debit is one of the most dangerous cash-flow structures a retailer can carry.
If you’re reading this because the debit hit again this morning and you’re doing math in your head about payroll, tobacco tax remittance, and the next fuel delivery invoice, this article is for you. There’s a way through stacked MCA debt in fuel retail, and it doesn’t require another advance to buy breathing room.
Why Fuel and Convenience Retail Gets Hit Harder Than Most
Underwriters like gas stations and convenience stores for one simple reason: revenue is high and steady. A station doing $2 million a year in gross fuel and merchandise sales looks like a strong credit on paper, so funders extend larger advances than the underlying margin can actually service. That mismatch, big top-line revenue, thin bottom-line margin, is exactly where MCA stacking takes root.
A few things make this industry uniquely exposed. First, fuel price volatility means gross revenue can swing 15-20% month to month with no change in unit volume, which throws off any advance sized against trailing bank deposits. Second, most stations run card-heavy transaction mixes, so a reconciliation clause, the contract provision letting the funder adjust your daily pull based on card volume, can spike the debit exactly when fuel margins compress. Third, tobacco and lottery licensing means a frozen or garnished bank account isn’t just a cash-flow problem, it can jeopardize the licenses the business depends on to sell its highest-margin products at all.
Owners in this position often take a second advance to cover the first one’s daily hit, then a third to cover the gap the second one created. Within a year, it’s common to see three or four funders debiting the same account, each one unaware of the others until a bank statement gets pulled during underwriting for the next one. The U.S. Small Business Administration and the Federal Reserve’s Small Business Credit Survey have both flagged this stacking pattern as a growing driver of small-business financial distress, particularly in cash-flow-thin, high-revenue sectors like fuel and convenience retail.
The UCC-1 Lien Nobody Explained to You
Nearly every MCA contract includes a UCC-1 financing statement filed against your business, your inventory, your equipment, and often your future receivables. It’s a public filing, and if you’ve taken more than one advance, you likely have more than one UCC-1 on record, each funder staking a claim to the same collateral pool. The Cornell Legal Information Institute’s summary of UCC Article 9 lays out how these security interests work and why filing priority, first in time, first in right, matters enormously when multiple funders are competing for the same dollars.
For a gas station, this collateral question gets more complicated than most retail businesses because fuel inventory itself, and sometimes the underground storage tanks and dispensers, can get swept into the lien language. If your funder agreement includes a lockbox or requires routing card receivables through a specific processor, that arrangement can also restrict your ability to switch processors or negotiate better card-processing rates, exactly when you need every basis point of margin you can find.
Some funders also include cross-default language: miss a payment to one funder, and every advance you’ve signed can technically go into default simultaneously. That’s part of why stacked MCA debt in fuel retail tends to escalate quickly once one payment gets missed. It’s also exactly the kind of provision a negotiated settlement needs to account for, because a UCC release has to be part of any resolution in writing, not just a verbal understanding that the debt is settled.
What a Negotiated Resolution Actually Looks Like
Here’s the good news: MCA balances in fuel and convenience retail get settled and restructured regularly, and the outcomes can be significant. We’ve seen stacked balances in this industry come down 70%, 80%, even higher in past negotiated settlements. Results vary and are not guaranteed, but the pattern holds because funders would rather recover a meaningful percentage of what they’re owed than push a business into total default and collect nothing.
There are generally two paths. A lump-sum settlement resolves the balance in one negotiated payment, usually the fastest route to getting UCC liens released and the daily debits stopped for good. A structured payment plan spreads a reduced, right-sized payment over months instead of the original punishing daily schedule, which works well when the business has real revenue but the current debit amount is simply unsustainable against fuel margins. Some owners in multi-advance situations also look at reverse consolidation, but that approach needs careful evaluation. It can create a new daily obligation on top of existing ones if the timing and structure aren’t handled correctly, so it’s not a fit for every stacked situation.
Large funders operating at scale, names like OnDeck Capital, Forward Financing, and Everest Business Funding among others in the space, generally have established settlement desks and processes precisely because they underwrite knowing a percentage of advances end up in workout. That’s not a knock on any specific company, it’s simply how the volume economics of MCA lending work, and it means a well-negotiated settlement conversation is a normal, expected part of the business for funders and borrowers alike.
A Composite Case: Three Funders, One Station
Consider a composite scenario built from patterns we see regularly: a single-location gas station and convenience store owner takes a first MCA for $60,000 to replace an aging fuel dispenser. Six months later, a slow winter and a spike in wholesale fuel prices squeeze margins, and a second advance for $45,000 covers the gap. By the following spring, the two daily debits combined exceed what the convenience-store side alone can service, and a third advance brings in $35,000 just to keep the doors open through the transition.
At that point, the owner is paying roughly $1,100 a day across three funders against a business generating maybe $400-600 a day in actual gross margin after cost of goods. The math doesn’t work, and it was never going to. In a negotiated resolution scenario mirroring outcomes we’ve seen in similar cases, an original combined balance in the $130,000-150,000 range gets resolved through structured settlements with each funder individually, often in the 65-75% reduction range from the original balances, freeing up the daily cash flow the station needs to actually operate. Every negotiation is different and depends on the specific funders, contract terms, and the business’s documented financials, but this general shape, multiple funders settled individually rather than all-or-nothing, is common in fuel and convenience retail workouts.
The IRS Doesn't Wait, Either
One thing that trips up gas station owners specifically: payroll tax deposits and fuel excise or tobacco tax remittances don’t pause because an MCA is draining the operating account. The IRS treats federal payroll tax deposits (Form 941) as a priority obligation, and falling behind on those while an MCA debit takes precedence in your account is a common and preventable mistake. If you’re triaging which bills get paid during a cash crunch, payroll tax deposits belong ahead of any MCA payment, not behind it.
This is general information about commercial business debt and isn’t tax advice for your specific filings, a CPA or tax professional should weigh in on your specific deposit schedule. But it’s worth flagging early: a good MCA restructuring plan accounts for tax priority obligations as part of the cash-flow picture, not as an afterthought once the funder conversation is settled.
Getting the Daily Debit Off Your Back
If you’re running a gas station or convenience store with two, three, or more MCA advances stacked against fuel margins that were never built to service that kind of daily draw, you are not out of options, and you are absolutely not the first station owner in this exact spot. The combination of high revenue and thin margin that made your business attractive to funders in the first place is also exactly the profile that responds well to a properly negotiated settlement or restructured plan.
The first move is understanding what you’re actually dealing with: how many UCC-1 filings are on record, what each contract’s reconciliation and cross-default language actually says, and what your true daily operating margin looks like once fuel cost of goods is stripped out. From there, a lump-sum settlement, a structured plan, or in some cases a Subchapter V filing through the Subchapter V small-business reorganization process can each be the right tool depending on how many funders are involved and how far behind the account already is.
Creditors may not always agree to proposed terms, every situation is different, and past performance does not predict future results. But the outcomes we’ve described here reflect real settlement patterns in fuel and convenience retail, not best-case hypotheticals. If daily debits are outrunning your margin, talk to an MCA Relief Specialist or a business attorney before the account goes further into distress. The sooner the real numbers are on the table, the more options are still on it too.
Photo credits: Featured image by SpotOn on Unsplash; Section 1 by Sergej ***** on Unsplash; Section 2 by iMin Technology on Unsplash; Section 3 by Vitaly Gariev on Unsplash; Section 4 by Ambre Estève on Unsplash; Section 5 by Giorgio Tomassetti on Unsplash; Section 6 by Jakub Żerdzicki on Unsplash; Section 7 by geralt on Pixabay.