
MCA Debt Priority: Which Funder to Settle First
When you're carrying multiple MCAs, settlement order matters as much as the negotiation itself. Here's how to sequence by lien position, COJ risk, daily cost, and funder behavior.
When You Have Multiple MCAs: Start Here
If you’re managing three, four, or five merchant cash advances at once, you already know what stacked advances feel like. The daily debits are relentless. Some mornings you’re watching your account balance before the next ACH hits, running the math on whether payroll clears before the next funder pulls. You’ve started thinking about settlement — you know you need to deal with this stack, not just survive it.
Here’s the question almost nobody tells you to ask: which funder do you go after first?
The order matters more than most business owners realize. The wrong sequence can trigger your most aggressive funder while you’re mid-negotiation with a cooperative one. The right sequence protects your bank account, manages legal exposure, and creates momentum that makes subsequent settlements easier to close. Getting out of a stack isn’t just about negotiating — it’s about negotiating in the right order.
This article walks through the four factors that should shape your settlement priority: lien position, confession of judgment exposure, daily cost, and each funder’s settlement behavior. If you’ve been carrying stacked MCAs and you’re ready to start climbing out, this is where to begin thinking.
UCC-1 Lien Position: First Filed, First Priority
Every MCA funder who follows standard practice files a UCC-1 financing statement against your business when the advance is issued. These filings establish a security interest — a legal claim — over your business assets, including future receivables. The first funder to file generally holds a superior lien position over those who filed later.
Under Article 9 of the Uniform Commercial Code, lien priority for most personal property — including receivables — follows the first-to-file rule. If you default and funders start competing for assets, the first filer gets paid ahead of junior lien holders. That structural advantage affects how each funder approaches negotiations.
Why does this matter for sequencing? Because junior lien holders have a weaker legal position — and that actually makes them more motivated to settle at a discount. They’d rather recover something now than fight for priority behind a senior holder who gets paid first. That makes junior-position funders attractive targets for early, deep settlements. Closing one or two junior positions quickly reduces your daily debit load and frees cash to tackle the senior funder next.
You can check your lien stack by requesting a UCC search from your state’s Secretary of State office — most states have searchable databases online. The filing timestamps tell you the order of priority, and that order becomes your foundation for sequencing.
COJ Exposure: Which Funders Can Move Fastest in Court
If any funder in your stack obtained a signed confession of judgment — a document where you admitted in advance to any future debt and waived your right to contest it — that funder holds the most dangerous legal tool in commercial collections. A funder with a valid, filed COJ can obtain a court judgment against your business with minimal legal process, then use that judgment to levy bank accounts or seize receivables.
New York, which was once the most common venue for COJ enforcement against out-of-state business owners, took significant action in 2019. Following the New York Attorney General’s investigation into abusive COJ practices against small business owners, New York banned the filing of out-of-state COJs against non-resident defendants. But COJs remain valid in several other states, and some funders continue to use them in jurisdictions where they’re still enforceable.
If a funder in your stack holds a signed COJ — especially in a state that processes them quickly — that funder needs to surface early in your assessment. Not because you have to pay them more, but because you need to know whether a judgment has already been filed and whether your bank account is at immediate risk. A business attorney can confirm that status in a single call. Getting that clarity early changes everything about how you sequence the rest of your settlements. COJ exposure is the one factor that can compress your timeline from weeks to hours.
Daily Cost Analysis: Which Advance Is Bleeding You Most
Not all advances cost the same per day. Some funders issued advances at factor rates of 1.15 — meaning a $50,000 advance requires $57,500 in total repayment. Others issued advances at 1.40 or 1.45, meaning that same $50,000 advance requires $70,000 to $72,500 back. Identifying which funder is costing you the most per day is straightforward math — but it’s math most owners carrying a stack haven’t actually done.
Take each advance, find the remaining payback balance (not the original principal — what you still owe), and divide by the number of payments remaining. That gives you the effective cost per payment period. The funder running you $480 per day is a higher settlement priority than the one running $150 per day — not just because it hurts more, but because settling the expensive one creates the most immediate cash flow relief.
The Federal Reserve’s Small Business Credit Survey has consistently documented that high-cost short-term debt is among the top financial stressors for small business owners, and that owners carrying multiple high-cost obligations are significantly more likely to face cash flow disruption. The daily debit math is exactly why. Prioritizing your highest-cost advance early accelerates your path to positive cash flow — and that freed-up cash is what funds subsequent settlements with the remaining funders in your stack.
Build a simple grid: funder name, original advance amount, factor rate, total payback, remaining balance, daily or weekly debit, payments remaining. That grid makes the priority decision almost obvious.
Funder Settlement Behavior: Who Deals vs. Who Fights
Understanding each funder’s settlement behavior is as important as understanding your lien position. Some of the largest MCA funders — Forward Financing, Everest Business Funding, OnDeck Capital, CAN Capital, Funding Metrics — operate at scale and have informal but established settlement processes. They’ve processed thousands of hardship accounts. They expect some percentage of their portfolio to end up in workout. The right approach, typically working through an experienced MCA Relief Specialist, can produce meaningful balance reductions because these funders would rather close a file at a discount than spend money on protracted collections.
Smaller or newer funders may behave very differently. Some escalate quickly to litigation or assign accounts to collection attorneys at the first missed payment. These funders often respond better to early, direct outreach before they hand the file off — because once a collection attorney is involved, the room to negotiate typically narrows and the cost of resolution goes up.
There’s also the regulatory dimension. The FTC has brought enforcement actions against MCA companies for deceptive practices — their enforcement cases and proceedings page documents actions against companies including RCG Advances and Yellowstone Capital. Funders that have been through regulatory scrutiny sometimes have altered settlement postures — and that context matters when you’re deciding how to approach a negotiation.
An MCA Relief Specialist who works in this space daily will know the behavioral patterns of major funders — who responds to written hardship proposals, who needs a phone call, who escalates fast and who doesn’t. That intelligence has real dollar value when you’re building your sequence.
Building Your Settlement Sequence: A Practical Framework
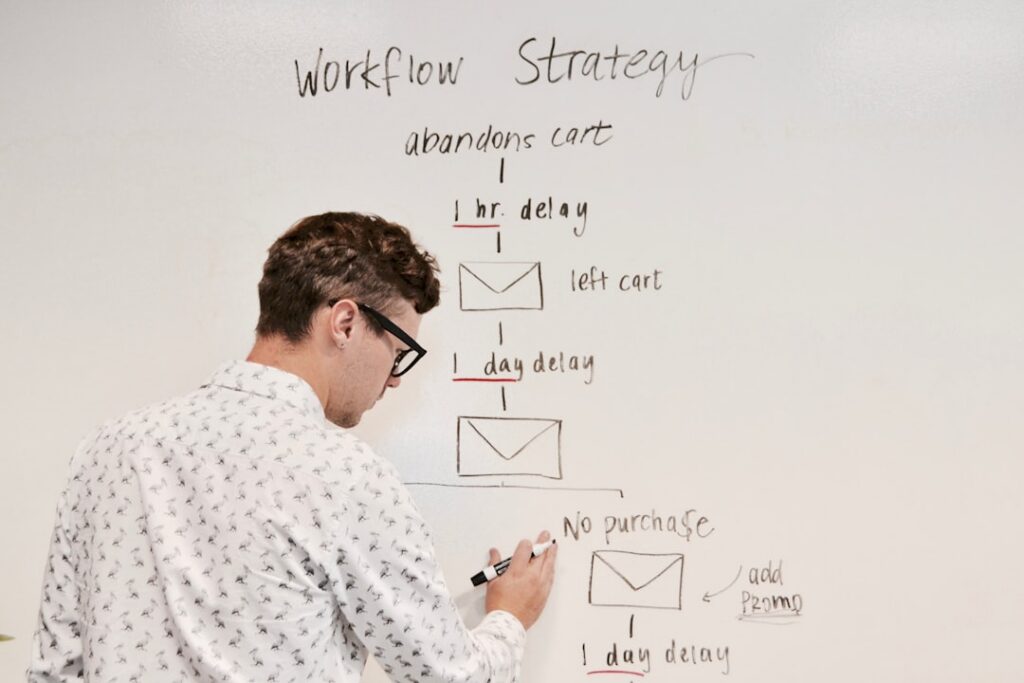
Once you’ve mapped your stack — lien position, COJ exposure, daily cost, funder behavior — you can build a settlement sequence instead of reacting to whoever is calling most aggressively. Here’s a practical framework that works across most stacked MCA situations:
- Assess COJ exposure first. A brief consultation with a business attorney confirms whether any funder has already obtained a judgment and whether bank account exposure is immediate. This information changes everything else in your sequence — address it before any other outreach.
- Open early conversations with your highest-cost funder. Even before you’re ready to close a deal, early engagement signals you’re working the problem — not disappearing. That usually slows escalation and keeps negotiating options open.
- Target junior lien holders for early settlements. These funders have weaker legal positions and often accept deeper discounts. Closing one or two junior positions quickly reduces your daily debit burden and frees cash for subsequent settlements.
- Use freed-up cash flow to fund settlements with senior funders. Once your daily burden drops, you can direct those savings toward lump-sum or structured settlements with the senior position holder — who typically requires more negotiation but also has more formal settlement processes in place.
The SBA’s business finance management resources can help you build a clear picture of your overall debt structure before you begin funder outreach — knowing your numbers cold is the foundation of any negotiation.
This isn’t a rigid formula — every stack is different. Some stacks have funders with overlapping lien scopes. Some have one dominant senior holder and several small junior ones. The sequencing logic flexes to your actual situation. But the principle holds: decide based on your map, not based on who called most recently.
What to Do Next: Map Your Stack Before You Move
Multiple MCAs don’t have to mean multiple disasters playing out in sequence. The business owners who emerge from stacked advance situations most successfully are the ones who take a breath, map the exposure, and make decisions strategically instead of reactively. Lien position, COJ risk, daily cost, and funder behavior are all factors you can understand — and once you understand them, you can sequence your way out instead of just bracing for impact.
Past settlements have produced reductions of 70%, 80%, even 90% on original balances through structured negotiation. A business carrying $160,000 across four funders is exactly the kind of situation where skilled, sequenced negotiation has resolved outstanding balances for dramatically less — redirecting that cash back into the business instead of into daily debits. Results vary and are not guaranteed, and past performance does not predict future results — but the pattern across completed settlements is consistent enough that it’s worth understanding what’s actually been possible.
If you’re carrying multiple advances and you’re not sure where to start, the right first step is a conversation with an MCA Relief Specialist who can pull your lien history, identify any COJ exposure, analyze your daily costs across funders, and build a settlement sequence tailored to your specific stack. This information addresses commercial business debt and is not consumer debt advice or legal advice for your individual situation. Creditors may not always agree to proposed terms, and every stack is different — but having a specialist in your corner who knows how these funders negotiate changes the conversation dramatically. You don’t have to figure out the order on your own.
Photo credits: Featured image by Emma Ou on Unsplash; Section 1 by Vitaly Gariev on Unsplash; Section 2 by Jonathan Cosens Photography on Unsplash; Section 3 by TheStandingDesk on Unsplash; Section 4 by Altnet on Pixabay; Section 5 by Kampus Production on Pexels; Section 6 by Campaign Creators on Unsplash; Section 7 by Vitaly Gariev on Unsplash.