
MCA Negotiation Leverage: What Gives You Power
Most business owners think they have no cards to play when MCA debt becomes unmanageable. Here's what actually gives you leverage at the settlement table.
You Have More Cards Than You Think
Here’s what most business owners in MCA trouble believe: the funder has all the power. They signed the contract. They owe the money. The daily ACH debits are already hitting. The UCC-1 is already filed against their business assets. The clock is ticking. What leverage could they possibly have?
More than they realize — a lot more.
MCA funders are running a numbers business. Every account in their portfolio is an asset they’re trying to maximize. When a business owner is genuinely struggling and a settlement makes more economic sense than a prolonged court fight, many funders will take it. Not out of generosity — because the math works for them too.
That’s what leverage actually means in MCA settlement negotiations: creating conditions where settling for less is the funder’s rational move. When you understand what drives those conditions — and how to present your situation strategically — the entire conversation changes. This article breaks down the four main leverage factors that experienced MCA relief specialists use when approaching funders. None require winning a legal argument. They require understanding how funders think, and positioning your situation accordingly.
What Leverage Actually Means in MCA Settlements
The term gets used loosely, but in MCA settlement negotiations, leverage has a specific meaning: anything that shifts a funder’s internal cost-benefit analysis toward accepting a reduced payoff rather than pursuing the full balance through enforcement.
MCA funders aren’t inflexible. They’re portfolio managers making calculated economic decisions at scale. According to the Federal Reserve’s Small Business Credit Survey, alternative lenders — the category that includes most MCA providers — have developed sophisticated portfolio management practices that include structured default resolution. Settlement is a known, expected, budgeted outcome in this industry. Funders plan for a percentage of their book to end up in workout.
Think of it this way: a funder who recovers $0.45 on the dollar this month beats a funder who recovers $0.00 three years from now after a drawn-out legal fight, attorney fees, and management time. When you can make settling the faster, cheaper, and more certain option, you have real leverage.
The goal isn’t to “beat” the funder — it’s to make saying yes to a negotiated resolution the smartest business move they can make. Each leverage factor below does exactly that from a different angle.
Leverage Factor 1: Documented Financial Hardship
The most fundamental source of leverage is the one most business owners underestimate: the documented reality of their financial position.
When a funder’s collections team opens a file and sees three consecutive months of declining bank deposits, bounced ACH debits, and a business clearly running on thin margins — they’re not just seeing a problem. They’re seeing a portfolio asset that may return very little if pushed hard through enforcement. A judgment against a business with no accessible cash is often worth almost nothing in practice.
Funders have seen thousands of businesses in distress. When the numbers tell a credible story of genuine hardship — not a business hiding assets, but one that truly cannot sustain current payment levels — the calculus shifts toward resolution. The documentation that matters most includes:
- Current bank statements showing real cash flow over the past three to six months
- A profit-and-loss statement reflecting declining revenue or compressed margins
- Context for the hardship — seasonal slowdown, major client lost, equipment failure, or market contraction
- Evidence of any missed or bounced debits already in the account history
The U.S. Small Business Administration notes that maintaining clean, current financial records is foundational to any creditor negotiation. Business owners with organized numbers move through settlement faster and typically achieve better terms — because the story the documents tell is clear, credible, and hard to dispute.
A skilled MCA Relief Specialist knows how to present this documentation not as a complaint or an excuse, but as a business case: here is the financial reality, here is what we can realistically offer, here is why this is the best outcome available for everyone.
Leverage Factor 2: The Reorganization Option Changes the Math
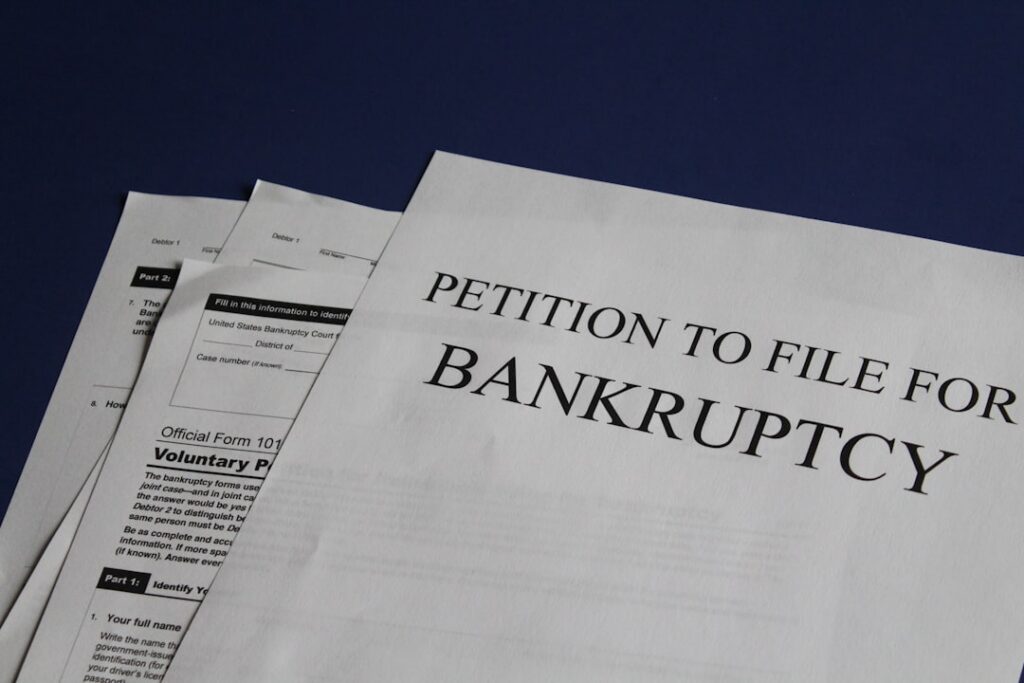
Here’s something MCA funders know well — and many business owners don’t: a legitimate Subchapter V Chapter 11 reorganization filing can change the entire negotiation dynamic.
Subchapter V, available to small businesses under the applicable debt threshold set by the U.S. Bankruptcy Code (verify current thresholds with a business attorney, as they have changed in recent years), allows small businesses to reorganize their debts — including MCA obligations — under court supervision. The business owner typically retains the business, proposes a repayment plan the bankruptcy court approves, and MCA funders may receive far less than face value, paid out over three to five years.
That’s a drastically different outcome than a voluntary lump-sum settlement for 40 cents on the dollar today — and funders know it.
Savvy MCA Options Specialists know when to put reorganization on the table as a credible, actively evaluated alternative. When a funder’s legal team runs the numbers and realizes they might wait four years for 12 cents on the dollar inside a reorganization plan versus receiving 35 cents today in a negotiated settlement, the voluntary resolution becomes genuinely attractive.
You don’t have to file for bankruptcy to use this leverage. A credible signal — a letter from a business attorney confirming Subchapter V is under active evaluation — can be enough to accelerate the conversation. What matters is that the threat is real, not a bluff. If the business qualifies and conditions deteriorate further, the filing option genuinely exists.
Leverage Factor 3: Multiple Funders Work Against Each Other
One of the most counterintuitive facts about MCA stacking is this: the more funders you have, the more leverage you may actually have in settlement negotiations — not less.
Here’s why. When four or five MCA funders are all competing for recovery from the same struggling business, they’re effectively in competition with each other. The funder who settles first gets paid. The funders who wait risk getting paid nothing — especially if the business eventually files for reorganization or simply closes.
This creates natural settlement urgency. Funders understand how this math works because they’ve seen it hundreds of times. A position-three or position-four funder — one whose UCC-1 filing sits behind earlier liens in priority order — has particularly strong incentive to settle early and for less, because they know their recovery in a worst-case scenario is minimal or nonexistent.
An experienced MCA Relief Specialist can leverage this dynamic strategically: approaching multiple funders simultaneously, creating competitive urgency, and closing settlements in a sequence that maximizes overall debt reduction across all accounts. In past cases, business owners carrying stacked advances across multiple funders have seen total balances resolved at substantial discounts — because each individual funder was motivated to settle rather than wait for a share of whatever might be left. Results vary and are not guaranteed, but the dynamic is real and it’s one of the most powerful tools in a structured negotiation.
The FTC’s enforcement actions against MCA companies have shed light on how these funders operate and collect — context that experienced specialists use when structuring negotiation approaches.
Leverage Factor 4: Enforcement Costs the Funder Too
This leverage factor is rarely discussed but consistently real: MCA enforcement is expensive for funders as well.
Filing a lawsuit, securing a judgment, pursuing a bank levy or asset garnishment, managing a portfolio of disputed accounts through multiple state court systems — all of this takes legal resources, management attention, and time. For large MCA funders managing hundreds or thousands of accounts simultaneously, the economics of all-out enforcement on every delinquent account simply don’t pencil out when compared to accepting a reasonable settlement and closing the file.
This reality has only deepened since New York’s 2019 COJ reform eliminated the confession-of-judgment shortcut that allowed funders to instantly obtain default judgments against business owners without a lawsuit. As documented by the New York Attorney General, these reforms force funders pursuing New York-based businesses to go through full civil litigation — a far slower, costlier process. In states with similar protections, voluntary settlement becomes relatively more attractive compared to months or years of litigation.
When you present a settlement offer through a credible representative — an MCA Relief Specialist or a business attorney — funders know they’re dealing with someone who understands the litigation math and the legal landscape. That shifts the dynamic from a collections call to a genuine business negotiation between parties who both have an interest in reaching a workable resolution.
Leverage Only Works When You Know How to Use It
Understanding these four leverage factors is the starting point — not the finish line. What actually moves the needle is how they’re deployed together, in the right sequence, by someone who negotiates with MCA funders regularly and knows which approaches land with which funders.
Most business owners who try to negotiate on their own face an immediate structural disadvantage: the funder’s collections team has done this hundreds of times this month. The business owner is doing it for the first time, under serious financial stress, without a clear picture of what the funder’s internal threshold for settlement actually looks like. That imbalance shows up directly in outcomes.
An experienced MCA Options Specialist knows which funders respond to hardship documentation, which ones accelerate under reorganization pressure, how to time multi-funder approaches to create urgency across the stack, and how to frame an offer in terms funders actually accept. Past settlements have reduced six-figure MCA balances by 70%, 80%, and in some cases more — because the leverage was genuine and applied with the right strategy. Past performance does not predict future results, and creditors may not always agree to proposed terms — every situation is different. But the framework works, and it’s available to you.
This information addresses commercial business debt and is not legal advice or consumer debt advice for your specific situation. Before you make any decisions about your MCA obligations — whether to continue paying, request hardship terms, pursue settlement, or explore reorganization — speak with an MCA Relief Specialist or a qualified business attorney. The conversation is confidential. What you learn about your actual options may change everything about how you approach the next step.
Photo credits: Featured image by Vitaly Gariev on Unsplash; Section 1 by Vitaly Gariev on Unsplash; Section 2 by geralt on Pixabay; Section 3 by Vitaly Gariev on Unsplash; Section 4 by Melinda Gimpel on Unsplash; Section 5 by Marvin Meyer on Unsplash; Section 6 by Kampus Production on Pexels; Section 7 by Vitaly Gariev on Unsplash.