
Food Truck MCA Debt: The Festival Season Cash Trap
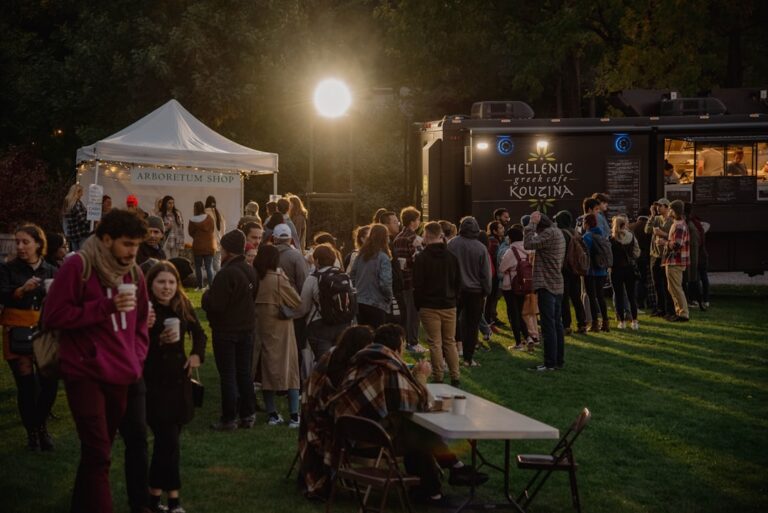
Food trucks feast on festival weekends and starve on rainy Tuesdays. Here's how that swing turns one MCA into a stack, and how owners get out.
Your Best Weekend Just Paid Off Three Advances You Don't Remember Signing Up For
Saturday was the county fair. You sold out of brisket by 3pm, the line wrapped around the truck twice, and you closed out the till thinking, finally, a real weekend. Then Monday morning the daily debit hits. Then Tuesday’s. Then Wednesday’s, on a day you didn’t even open because the truck was in the shop. By Thursday you’re transferring money from a personal account to cover a shortfall on a business that, three days ago, felt like it was finally working.
If that whiplash sounds familiar, you’re not imagining it. Food truck revenue doesn’t arrive on a steady curve the way a fixed storefront’s does. It spikes at festivals, fairs, breweries with rotating truck nights, and private catering gigs, then drops to almost nothing on a slow weekday with no events booked. A merchant cash advance doesn’t care about that rhythm. It debits your account on a fixed schedule regardless of whether today was a fairground sellout or a day the truck never left the commissary lot.
That mismatch is exactly how one advance for a new fryer or a wrap job becomes two, then three, then four. This article walks through why that happens, what the contract terms actually mean for your cash flow, and what real options exist once you’re in it. There is a way through stacked MCA debt that doesn’t involve chasing down another festival booking just to make Friday’s debit.
Why Funders Love Food Trucks (and Why That's a Problem)
Mobile food businesses are attractive to MCA funders for a specific reason: most run every sale through a card reader, which gives the funder a clean, verifiable revenue stream to underwrite against. A truck doing $9,000 a month in card sales looks fundable on paper, even if $6,000 of that came from two festival weekends and the rest trickled in on slow weekdays.
The advance itself isn’t structured as a loan — legally and contractually, it’s a purchase of a percentage of your future receivables, which is part of why MCAs sidestep state usury caps that apply to traditional lending. The Cornell Legal Information Institute’s overview of usury law explains why that receivables-purchase structure matters: it’s the legal basis funders rely on to charge what would be an illegal interest rate on a conventional loan.
What you actually get instead of an interest rate is a factor rate — a flat multiplier, commonly between 1.2 and 1.5, applied to the amount advanced. Borrow $30,000 at a 1.4 factor and you owe $42,000 back, full stop, regardless of how fast or slow you pay it. Divide that $42,000 into fixed daily or weekly debits over a short term, often three to nine months, and you get a payment obligation that has nothing to do with whether this particular week included a festival.
The Real Math: Festival Income vs. Fixed Daily Debits
Picture a taco truck that takes a $25,000 advance at a 1.35 factor rate to cover a new generator and a menu-board wrap. That’s $33,750 owed back, structured as a $375 daily debit, five days a week, for about 18 weeks.
On a festival Saturday doing $2,200 in sales, that $375 is nothing — it disappears into the register before lunch rush ends. On a Tuesday with no bookings and $180 in walk-up sales from the commissary lot, that same $375 debit doesn’t just eat the day’s revenue. It goes negative, and the bank either bounces the transaction or dips into money set aside for propane, payroll, or next week’s food order.
Owners in this position often do the same thing: they take a second advance to smooth over the gap the first one created. Now there are two daily debits stacked on top of each other, and the math that barely worked with one advance is underwater with two. This is the stacking spiral, and it typically doesn’t happen because an owner made a bad decision — it happens because event-based revenue and a fixed daily obligation were never compatible to begin with.
UCC-1 Liens on Your Truck, Equipment, and Everything Else
Most MCA contracts include a UCC-1 filing — a public lien the funder records against your business assets, which for a mobile food operation often explicitly names the truck, the kitchen equipment, and sometimes accounts receivable from catering contracts. A U.S. Small Business Administration overview of funding options is a useful place to see how MCA financing compares structurally to SBA-backed products, which don’t carry the same daily-debit repayment mechanic.
Stack three or four advances and you can end up with three or four separate UCC-1 filings against the same truck, each one recorded in the order the funder filed it. That filing order matters more than most owners realize: if you ever try to sell the truck, refinance, or bring in an equipment lender, whoever holds the earliest-filed UCC-1 typically gets paid first. A later funder is negotiating from a weaker position — which, worked correctly, actually gives an owner leverage in a resolution conversation.
Most MCA contracts also include a personal guarantee, meaning the funder can pursue you individually, not just the business entity, if the truck’s LLC can’t pay. And in states that still permit them, some contracts include a confession of judgment clause — a signed admission of default that lets a funder go straight to a court judgment without a hearing if you miss debits. New York banned COJs against out-of-state small businesses back in 2019; the NY Attorney General’s announcement on that ban is worth reading if your contract was filed under New York’s jurisdiction, which many are regardless of where the truck actually operates.
Options That Actually Exist Once You're Stacked
The instinct when the debits stop working is to look for a fifth advance to cover the first four. That’s the trap talking, and it’s exactly how a $25,000 problem becomes a $90,000 one. There are other paths, and they’re used every day by mobile food operators in exactly this position.
A hardship request asks a funder directly to reduce the daily debit or pause payments temporarily, usually backed by recent bank statements showing the mismatch between event income and fixed obligations. A structured payment plan renegotiates the schedule into something that actually fits a seasonal revenue pattern instead of a flat five-day-a-week debit. A lump-sum settlement resolves the full balance for less than what’s contractually owed, typically funded by a combination of reserved cash and, where it makes sense, a reverse consolidation that replaces several daily debits with one manageable payment.
ACH revocation — formally withdrawing your bank’s authorization to debit the account — is a real legal option under banking regulations, but it’s a last resort that can trigger default and acceleration of the full balance owed, so it should never be the first move without a negotiated plan already in place. For businesses carrying enough stacked debt that none of the above fully solves it, Subchapter V of the Bankruptcy Code offers a streamlined reorganization path built specifically for small businesses; the U.S. Courts’ overview of Subchapter V lays out how that process works.
Timing It Right Before Fall Festival and Holiday Market Season
Late August is a specific moment for mobile food operators. Fall festival circuits, harvest markets, and holiday pop-up events are about to book out, and many owners are staring down inventory and equipment costs to gear up for what’s historically the busiest run of the year. That’s exactly the wrong moment to walk into fall already stacked on daily debits from spring and summer advances.
The Federal Reserve’s Small Business Credit Survey has consistently found that MCA and other online financing products carry among the highest dissatisfaction rates of any small-business credit type, largely tied to repayment structure rather than access. Mobile food operators are a near-perfect example of why: the product’s fixed-debit design fights against exactly the kind of seasonal, event-driven income this industry runs on.
Getting current advances resolved or restructured before the fall booking season starts means walking into your biggest quarter with cash flow that can actually absorb a rainy weekday, instead of one that snaps the moment a festival gets rained out.
What to Do Before Your Next Booking Season
If you’re reading this because you did the math on next week’s debits and it doesn’t work, you’re already ahead of where most owners are when they finally ask for help. The fix isn’t skipping meals to cover the debit or hunting down one more weekend booking to survive the week — it’s getting the debt itself restructured into something your actual revenue pattern can support.
We’ve seen stacked balances brought down significantly — 70%, 80%, sometimes more — through negotiated settlements and structured plans built around a business’s real cash flow rather than a generic repayment calendar. Results vary and are not guaranteed, and creditors may not always agree to proposed terms, but funders who do this at volume generally have an established process for resolving accounts rather than pursuing every default through litigation.
This is general information about commercial business debt, not consumer debt advice, and it isn’t a substitute for advice on your specific contracts. Before you sign anything else or let another debit bounce, talk with an MCA Relief Specialist or a business attorney who can look at your actual advance agreements, UCC filings, and bank statements and lay out which path — hardship modification, structured plan, lump-sum settlement, or something more — fits your truck’s real season.
Photo credits: Featured image by Daulet Rakhymzhan on Unsplash; Section 1 by Joshua Ferrer on Unsplash; Section 2 by Zaur Giyasov on Unsplash; Section 3 by Mediamodifier on Unsplash; Section 4 by zapCulture on Pixabay; Section 5 by Lalmch on Pixabay; Section 6 by Nataniel Susantoputra on Unsplash; Section 7 by Nathan Sack on Unsplash.