
Snow Removal MCA Debt: Financing Before Winter
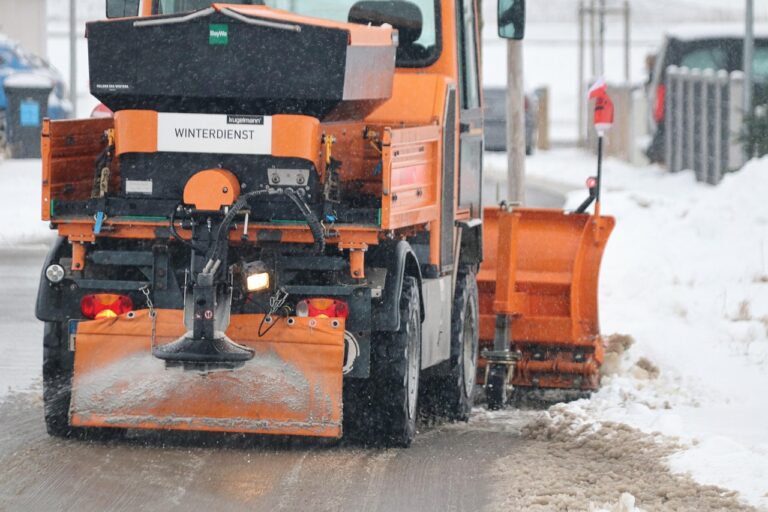
Snow removal contractors gearing up for winter are stacking MCA debt to buy plows and salt. Here's how to finance the season without the daily-debit trap.
The Plow's Ready. Is Your Cash Flow?
Late September is when snow removal contractors either get ahead of winter or fall behind it for good. The trucks need plows mounted, the salt bins need filling, the seasonal crew needs to be locked in before someone else hires them first — and none of that is cheap. If your landscaping or lawn care revenue just went quiet for the fall shoulder season, the timing could not be worse.
So a lot of owners do what feels like the only option: they take a merchant cash advance against next month’s card swipes to cover plows, salt, and payroll now, betting that the first big storm will bail them out. Sometimes it works. Often it doesn’t, because the advance doesn’t know your business is seasonal. It debits your account every single business day, storm or no storm, October or January.
If you’re reading this because you already did that — maybe more than once — you’re not the first snow contractor to land here, and there’s a real way out that doesn’t involve another advance. Let’s walk through why this trap is so specific to seasonal operators, and what actually works to get out of it.
Why MCA Underwriting Doesn't Understand Seasonal Revenue
Merchant cash advance underwriting looks backward, not forward. Funders pull three to six months of bank statements and deposit history, average out your daily card volume, and size the advance and the repayment schedule off that number. It’s fast — often same-day — which is exactly why it’s tempting when you need equipment and salt inventory before the first frost.
The problem: a snow removal or landscaping business doesn’t have flat revenue. You might run strong from April through September, go quiet in October and November, and then spike hard in December through February once storms hit. An MCA doesn’t adjust for that curve. The Federal Reserve’s Small Business Credit Survey has repeatedly found that seasonal and cash-flow-uneven businesses are among the most likely to turn to high-cost online funding precisely because traditional lenders won’t underwrite the gap — and MCA funders are happy to step in, at a price.
That price is the factor rate, not an interest rate. A $60,000 advance at a 1.40 factor means you owe $84,000 back, collected in daily debits sized to hit that total in a fixed number of business days — regardless of whether your equipment is sitting idle waiting for snow.
The Equipment Financing Trap
Here’s where it gets worse for snow contractors specifically: plows, spreaders, and salt brine systems are real, financeable business assets. They hold value. They’re exactly the kind of purchase equipment loans and SBA-backed financing exist for. But equipment lenders want paperwork, a credit pull, and a few days to close — and when your crew needs to be plow-ready by the first weekend in November, a few days can feel like forever.
So the advance goes to buying a truck attachment or a season’s worth of bulk salt instead, and now you’ve financed a depreciating, revenue-generating asset with the most expensive capital available, repaid on a daily schedule that has nothing to do with when that asset actually earns money. The U.S. Small Business Administration’s loan programs exist in part to solve exactly this mismatch, but most seasonal operators never get quoted an SBA option before the MCA broker calls back with same-day funding.
Watch for the reconciliation clause buried in your MCA contract, too — the provision that’s supposed to let you request a lower debit during a slow stretch. On paper it sounds like exactly the seasonal relief a snow contractor needs. In practice, funders can make it painfully hard to actually invoke, and plenty of owners don’t find out how narrow it is until they try to use it in a quiet October.
When the Debits Outrun the Season
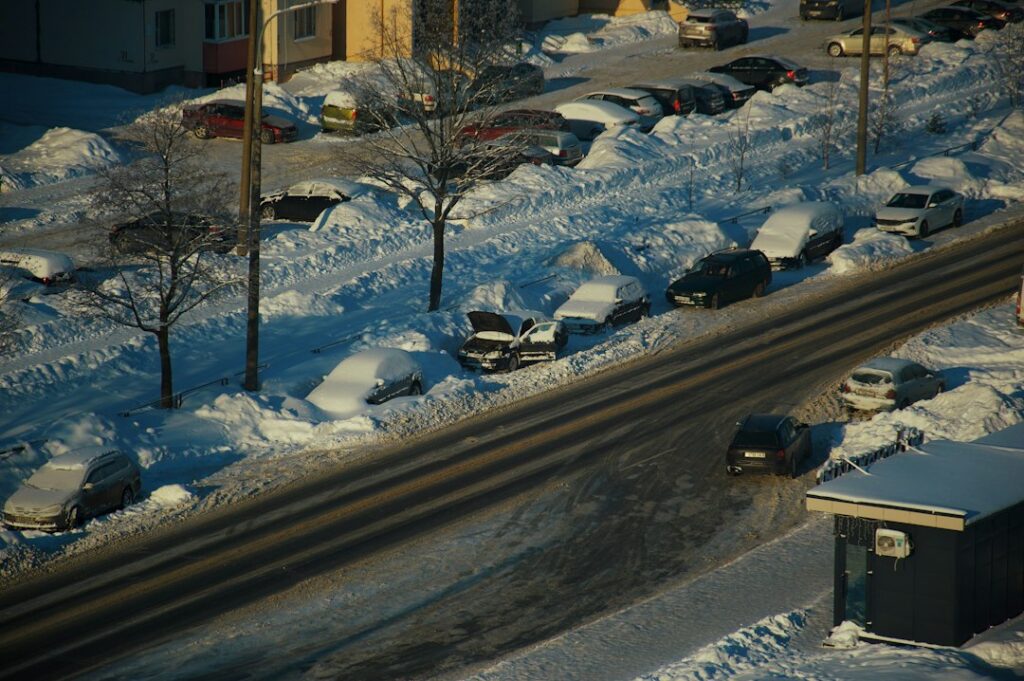
The math breaks in a specific, predictable way for snow removal operators. You take the advance in September to gear up. October and early November stay quiet — no snow yet, but the daily debit doesn’t care. By the time the first storm finally hits in late November or December, you’re already three or four months behind on repayment, the balance has ballooned with fees, and now storm revenue is going straight to catching up the MCA instead of building a cushion for January and February, historically the heaviest snow months in most of the country.
If a debit bounces because the account can’t cover it, most MCA contracts treat that as a default trigger. From there, funders can accelerate the full remaining balance, and many contracts include a UCC-1 lien filed against your business assets — which, for a snow removal operation, often specifically includes the trucks and plow equipment you just financed the advance to buy. If a personal guarantee was signed, and most MCA contracts require one, your own assets can be exposed too.
The FTC has taken enforcement action against MCA companies over undisclosed fees and aggressive collection tactics in recent years, which is worth knowing — but it doesn’t undo a contract you already signed. Once you’re behind, the priority isn’t proving a funder acted badly. It’s getting ahead of the debit schedule before storm season revenue gets swallowed whole.
Stacking Advances to Survive the Shoulder Season
The most common failure pattern we see with seasonal operators isn’t one advance — it’s two or three, taken in sequence, each one plugging the hole the last one dug. A September advance for equipment. A second advance in October when the first debit schedule turns out to be unsustainable against zero snow revenue. Sometimes a third, once a broker calls offering to “help” with a top-up.
Each additional advance sits in a lower priority position behind the ones before it, and each one adds its own daily debit on top of the others. By December, a contractor who needed $50,000 to gear up for the season can be carrying six figures in combined MCA debt across three or four funders, with combined daily debits that exceed what the business can generate even during peak storm weeks. This is the stacking spiral, and seasonal businesses fall into it faster than almost any other industry because the underwriting mismatch compounds every time a new advance gets layered on.
Real Options Before You Take Another Advance
If you’re already stacked heading into winter, taking a fourth advance to cover the third one’s debit is the move that turns a bad season into a permanently unstable business. There are better paths, and they don’t require abandoning the season or the equipment you’ve already financed.
A negotiated resolution with your existing funders can restructure the daily debit into something the business can actually sustain through a slow October, often paired with a lump-sum settlement once storm revenue builds a cushion. We’ve seen six-figure stacked balances brought down 70%, 80%, even higher in past settlements through structured negotiation directly with funders. Results vary and are not guaranteed — every funder, every contract, and every business’s numbers are different — but the pattern of significant reductions is real and it’s documented in completed cases.
Reverse consolidation can also help by replacing scattered daily debits from multiple funders with a single structured payment sized to what the business can handle. And if the balance sheet is far enough underwater that even a settlement can’t fix it, Subchapter V of the bankruptcy code, built specifically for small businesses, is worth understanding before default forces the decision for you — the U.S. Courts’ overview of Chapter 11 basics is a good starting reference before that conversation.
The Bottom Line for This Season
Winter is coming whether the financing is clean or not, and a snow removal business with the right equipment and a sustainable payment structure behind it can have a genuinely strong season. The trap isn’t seasonal financing itself — it’s financing it with daily-debit debt that ignores the calendar completely. There is a way to get the plows mounted and the salt bins full without setting January up to be a repayment crisis.
This is general information about commercial business debt, not consumer debt advice, and it isn’t a substitute for advice tailored to your specific contracts and numbers. Creditors may not always agree to proposed terms, and every negotiation depends on the specific funders and balances involved. For guidance on your own situation — whether that’s restructuring an existing stack, settling before the season locks you in further, or figuring out whether equipment financing can still work — speak with an MCA Relief Specialist or a business attorney before the first storm hits. Past performance does not predict future results, but knowing your options now, while there’s still time before peak season, is the difference between a profitable winter and another year of digging out from daily debits.
Photo credits: Featured image by planet_fox on Pixabay; Section 1 by Rana Singh on Unsplash; Section 2 by Sajad Nori on Unsplash; Section 3 by sdg_Rai on Pixabay; Section 4 by Timofey Radkevich on Unsplash; Section 5 by marcelkessler on Pixabay; Section 6 by Paul White on Unsplash; Section 7 by Chris Alo on Pexels.