Vending Machine MCA Debt: Route Cash vs Daily Debits
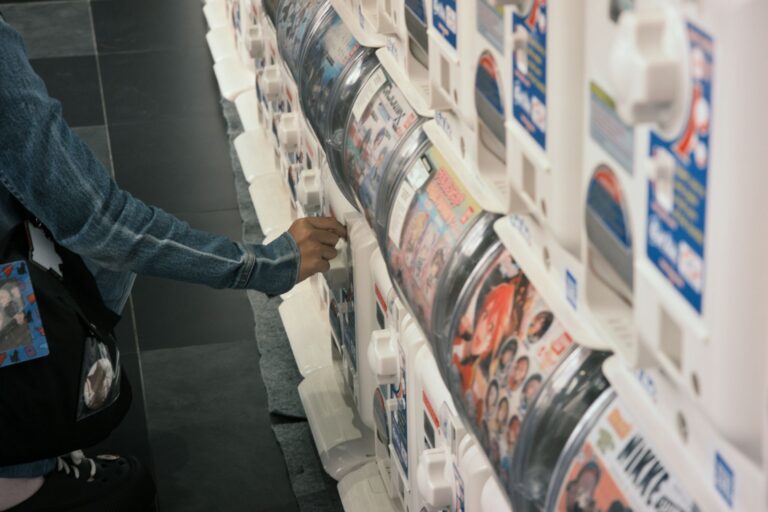
Vending and micro-market operators collect revenue in route cycles, not daily deposits. That mismatch is why MCA debt hits this industry so hard.
Your Revenue Runs on a Route. Your MCA Debt Doesn't Care.
If you run vending machines or micro-markets, you already know your business doesn’t work like a retail storefront. Cash and card revenue comes in on a route cycle, machine by machine, location by location, collected and reconciled over days, not deposited in real time the way a cafe’s card swipes hit the bank. A merchant cash advance doesn’t know that. It debits your account every morning or every week regardless of where you are in the collection cycle, and that mismatch is exactly why so many route operators end up stacked with two, three, even five advances before they realize what’s happening.
You’re not alone in this, and you’re not stuck. Vending and micro-market operators are exactly the kind of business that MCA companies target hardest, because route-based cash flow looks unpredictable on paper even when the underlying business is healthy. The good news is that once you understand why the math breaks down, there’s a clear path to fixing it, and it doesn’t require taking out another advance to cover the last one.
This article walks through how daily debits collide with route-cycle revenue, what stacking looks like in this industry specifically, and what a real path to relief looks like when the debits stop matching the deposits.
Why Route-Based Businesses Get Hit Harder Than Most
Most MCA underwriting is built around a simple assumption: revenue flows into a single business bank account on a predictable daily basis, so a daily or weekly ACH debit is a safe, proportional draw against it. Vending and micro-market operations break that assumption in three ways. First, collections are physical and route-scheduled. Coin and cash from a machine in one location might not get counted and deposited for a week. Second, card revenue from cashless readers often batches through a third-party processor before it lands in your account, adding another lag. Third, revenue is spread across dozens or hundreds of individual machines, each with its own cycle, so total deposits can swing widely week to week even when total sales are steady.
A funder that underwrites off three months of bank statements sees that lumpiness and often responds by offering a smaller advance with a higher factor rate to compensate for perceived risk, or by structuring the daily debit aggressively to get repaid fast before the next lumpy week. Either way, the debit schedule is built around bank-statement averages, not around when your route actually puts money in the account. That’s a structural mismatch, not a sign you’re running the business wrong.
According to the Federal Reserve’s Small Business Credit Survey research, cash flow volatility is one of the top reasons small firms turn to high-cost, fast-funding products like merchant cash advances in the first place, and it’s also one of the top reasons those same products become unmanageable once payments start.
The Reconciliation Clause Most Route Operators Never Read
Buried in most MCA contracts is a reconciliation clause, language that in theory lets you request an adjusted debit amount if your actual revenue drops below what the funder projected. On paper, this should protect a route business during a slow collection week. In practice, most reconciliation clauses require you to proactively request the adjustment, provide documentation, and get funder approval, all while the daily debit keeps hitting your account exactly as scheduled. Very few route operators know this clause exists until they’re already three advances deep and searching their contracts for a way out.
This is where the underlying legal reality matters: an MCA is structured as a purchase of future receivables, not a loan, which is why it isn’t subject to state usury caps the way a conventional business loan would be. The Cornell Legal Information Institute’s overview of merchant cash advances explains this structural distinction and why it shapes how aggressively these contracts can be written.
Some states have started requiring more transparency here. New York’s commercial financing disclosure law, enforced through the New York Department of Financial Services, now requires funders to disclose an estimated APR-equivalent and payment schedule up front. California’s DFPI has a similar commercial financing disclosure rule. If your contract predates one of these disclosure requirements, or your funder operates in a state without one yet, you may never have seen the true cost spelled out in a way you could compare across offers.
How Stacking Happens in a Route Business Specifically
The stacking pattern in vending and micro-market operations tends to follow a predictable arc. An operator takes a first advance to fund a route expansion or a batch of new machines, priced against trailing bank statements that don’t fully capture the route’s true earning potential once new locations ramp up. The debit schedule is tight from day one. A slow month, an equipment breakdown, a location that cancels its contract, any of these can leave the account short on debit day.
To cover the shortfall, the operator takes a second advance, often from a different funder who sees the first advance already on the books and prices even more conservatively. Now two daily debits compete for the same route-cycle cash. A third follows the same pattern. This is what the industry calls stacking, and it’s especially punishing for route businesses because the underlying revenue timing problem never gets fixed. Each new advance just adds another daily draw against cash that was already lagging behind its collection cycle.
By the time most operators reach out for help, they’re managing four or five separate daily debits against one route’s worth of revenue, and the math simply doesn’t close. That’s not a failure of the business. It’s what happens when a financing product designed for predictable daily deposits gets applied to a business model built around scheduled collections.
What a UCC-1 Filing Means for Your Machines and Locations
Most MCA contracts include a UCC-1 filing against your business assets, and for a route operator that can include the machines themselves, the inventory inside them, and your accounts receivable from location contracts. This is a public lien filing, and it matters most when you’re trying to expand, refinance, or sell the business, because a lender or buyer will see every funder in line ahead of them. The Uniform Commercial Code Article 9 overview at Cornell LII covers how these security interests work and what it takes to release one.
If you’ve stacked multiple advances, you likely have multiple UCC-1 filings layered against the same assets, filed in the order the advances were taken. That filing order becomes relevant in any negotiated resolution, because it often determines who has the strongest claim and who has the most incentive to settle rather than litigate. This is exactly the kind of detail an experienced negotiator uses as leverage, and exactly the kind of detail that’s nearly impossible to sort out on your own while you’re also trying to run daily collections.
Some operators also worry about confessions of judgment. Since New York banned out-of-state COJs against New York businesses in 2019, this tool has become far less common nationally, but it’s worth knowing whether your contract includes one and where it’s enforceable before a dispute ever reaches that stage.
The Fix: Structured Resolution Built Around Real Cash Timing
Here’s the part that matters most: this is fixable, and it doesn’t require another advance. A negotiated resolution restructures what you owe around your actual route-cycle cash flow instead of forcing your collections to match someone else’s debit schedule. That can mean a lump-sum settlement funded once you’ve built up reserve cash, a structured payment plan with debits sized to your real collection timing, or in more complex stacked cases, a reverse consolidation that replaces multiple daily debits with a single, more manageable payment.
We’ve worked cases where a route operator carrying $180,000 across four stacked advances settled the combined balance for roughly $65,000, a reduction of nearly two-thirds. We’ve seen individual settlements go even further, into the 70%, 80%, and occasionally 90% range depending on how many funders are involved and how far the account has already gone into default. Every case is different, and results vary and are not guaranteed, but the pattern is consistent: funders would rather negotiate a resolved balance than chase a route operator through the reconciliation process indefinitely.
Funders across this space, from large national players to smaller regional shops, have established settlement processes precisely because they know a percentage of advances end up needing one. That’s not a weakness in the system. It’s an opening, and the right specialist knows how to use it.
What to Do Next
If your route is carrying two or more MCAs and the daily debits are outrunning your collection cycle, the worst move is taking a new advance to cover the next one. That just adds another daily draw to a cash flow problem that’s already structural. The better move is understanding your actual options: reconciliation requests, hardship petitions, structured settlement, or in more serious cases, a Subchapter V filing under the small business provisions the U.S. Courts explain in their Chapter 11 basics guide.
This information addresses commercial business debt for route-based operators specifically, not consumer debt advice, and it isn’t a substitute for legal counsel on your particular contracts. Creditors may not always agree to proposed terms, and every funder relationship is different, but past performance on cases like these shows real, substantial reductions are possible when the negotiation accounts for how your revenue actually moves.
If daily debits are consistently outrunning what your route brings in, don’t wait for a bounced payment to force the conversation. Speak with an MCA Relief Specialist who understands route-based and micro-market cash flow, or consult a business attorney, before your next debit date. There’s a way to get your collection cycle and your payment schedule back in sync, and it starts with one conversation.
Photo credits: Featured image by Qeis Ismail on Pexels; Section 1 by blickpixel on Pixabay; Section 2 by Mathieu Turle on Unsplash; Section 3 by Signature Pro on Unsplash; Section 4 by Corina Rainer on Unsplash; Section 5 by Rafael Hoyos Weht on Unsplash; Section 6 by Fotógrafo Samuel Cruz on Unsplash; Section 7 by Centre for Ageing Better on Unsplash.