
MCA Debt for Wedding Venues: Deposit Timing Risk
Deposits collected today are for weddings a year from now. That timing gap is exactly what makes MCA debt so risky for event venues.
Money in the Bank Isn't Always Money You Can Spend
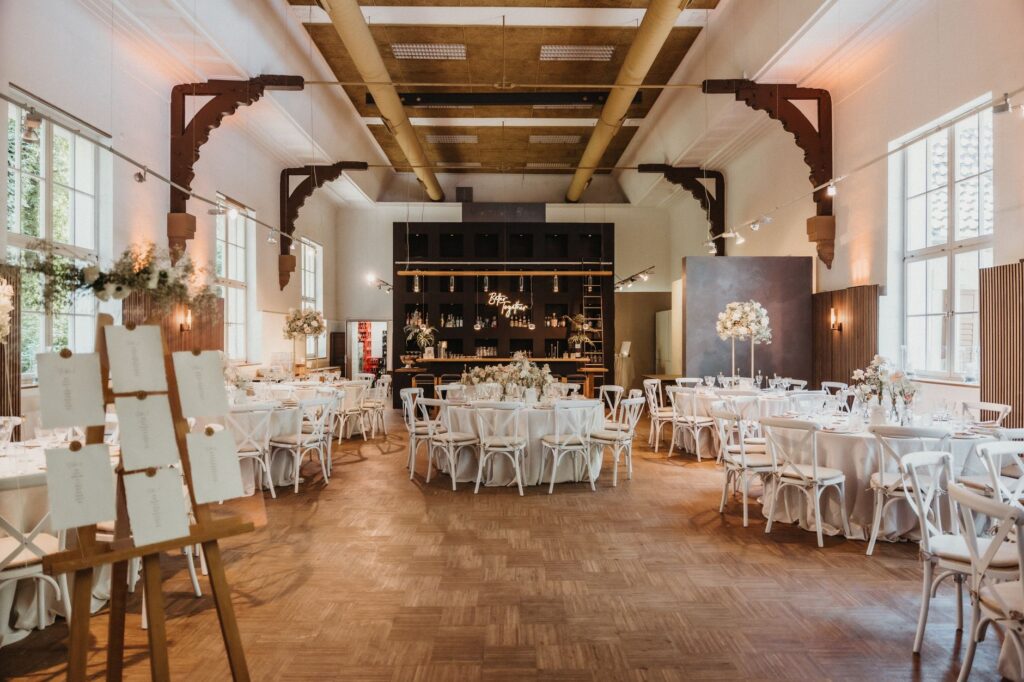
A wedding and event venue has a strong booking season — couples locking in dates a year or more out, each paying a deposit to hold the day. The bank account looks healthy, an MCA gets sized against that deposit activity, and the daily debit begins. Then the calendar moves forward: a few cancellations come in with contractual refund obligations, the actual events tied to those deposits are still months away, and the debit that looked perfectly reasonable during peak booking season suddenly doesn’t match what the account can actually support.
Event venues run on a revenue model that looks deceptively simple from a bank statement but is genuinely unusual: money collected today is very often payment for a service that won’t be delivered for a year or more, and a real portion of it may need to be refunded if the event doesn’t happen as planned. This article explains why that timing gap makes MCA debt an especially risky fit for venues, and what actually works when a venue is already carrying it.
Why Deposits Aren't the Same as Earned Revenue
MCA underwriting typically looks at recent bank deposit activity as a proxy for the business’s real revenue capacity. For a retail store or restaurant, that’s a reasonable proxy — a sale today is revenue the business has actually earned today. For an event venue, a deposit collected today is fundamentally different: it’s advance payment tied to a specific future date, often held under a contract that includes cancellation terms, partial refund obligations, and sometimes requirements around how those funds are used before the event occurs.
A debit sized against a strong deposit-collection month can badly misjudge how much of that cash the venue can actually treat as free operating capital. Some portion of recent deposits may need to remain available to cover event-specific costs down the line, or to be refunded entirely if a booking falls through — neither of which shows up as a distinction on a simple bank statement, and neither of which an MCA debit schedule accounts for.
The Cancellation Refund Risk MCA Debits Don't See
Most venues operate under cancellation policies that require partial or full refunds under certain conditions, and expectations around flexible cancellation terms have only grown among couples booking events. When a cancellation triggers a meaningful refund on a deposit collected weeks or months earlier — a deposit an MCA funder’s underwriting already counted as part of the venue’s revenue base — the venue can be caught genuinely short. Unlike a typical retail return, an event deposit refund is often large relative to the venue’s daily cash flow, since venues tend to have fewer, higher-value transactions rather than many small ones.
That mismatch is exactly why a string of cancellations can hit a venue’s ability to cover an existing MCA debit far harder than an equivalent revenue dip would hit a business with more numerous, smaller transactions. The debit schedule doesn’t pause or adjust for a refund obligation the venue is contractually required to honor.
Why Good Cash Management Matters More Here
Because MCA debits are calculated against raw deposit activity rather than the venue’s real obligations tied to those deposits, disciplined internal cash management becomes especially important. Keeping a clear internal accounting of which deposits are tied to upcoming events, what refund exposure exists on each booking, and what’s genuinely available as working capital helps a venue owner see a debit mismatch coming before it becomes a crisis. The U.S. Small Business Administration’s guidance on managing business finances is a useful starting point for building that kind of clarity, and pairing it with a business bank account structure that keeps future-event deposits reasonably distinguishable from discretionary operating cash — the SBA’s guidance on opening and structuring a business bank account is a good starting reference for that separation.
What Actually Works When the Mismatch Has Already Hit
For a venue already carrying MCA debt that no longer fits its real cash position, documenting the actual booking-to-event timeline and any pending cancellation exposure is the strongest tool in a negotiation. A funder evaluating a settlement or restructured plan responds very differently to a clear picture of upcoming confirmed events and their expected payment timing than to a flat assumption that recent deposit activity represents available cash. Broader financing data underscores how little room for error most small businesses have to begin with — the Federal Reserve’s ongoing research into small business financing conditions consistently finds thin cash buffers across small firms, which is exactly why a debit schedule built around the wrong revenue assumption can escalate quickly for a venue.
A negotiated resolution structured around the venue’s real event calendar — concentrating payments around confirmed upcoming events rather than a flat daily amount — tends to be far more sustainable than trying to force the existing schedule to work through a run of cancellations.
A Composite Case: The Cancellation Cluster
Consider a composite scenario built from patterns seen across many small businesses: an event venue took an MCA sized against a strong deposit-collection season, with dozens of couples booking dates over a year out. A cluster of cancellations tied to a regional economic downturn triggered several contractual refunds within a short window, at the same time daily MCA debits were still calculated against the original, stronger deposit activity. The combination pushed the venue into repeated overdrafts within weeks.
Working with a specialist to document the venue’s actual confirmed booking calendar and remaining refund exposure, the MCA balance of roughly $69,000 was resolved through a negotiated settlement at approximately $22,000, close to a 68% reduction, with a restructured schedule aligned to the venue’s real event timing going forward. Results like this happen regularly once a funder sees a clear, documented picture of a venue’s actual booking cycle, but results vary and are not guaranteed, and every venue’s cancellation policy and every funder’s terms are different.
Match Financing to When the Event Actually Happens
A deposit collected today and an event held a year from now are two very different points in time, and MCA debt structured around the moment of collection rather than the moment of service ignores that gap at real risk to the venue. Building financing and cash management around the venue’s actual booking-to-event timeline — not just recent deposit activity — is what prevents this mismatch from becoming a crisis in the first place.
Creditors may not always agree to proposed terms, and every situation is different, but a resolution built around a venue’s real event calendar is very often achievable. Speak with an MCA Relief Specialist or MCA Options Specialist who can build a plan around your venue’s actual booking and cancellation picture, or a business attorney for contract-specific questions. This information addresses commercial business debt and is not consumer debt advice or a substitute for guidance tailored to your specific venue and contracts.
Photo credits: Featured image by RDNE Stock project on Pexels; Section 1 by Masood Aslami on Pexels; Section 2 by epicioci on Pixabay; Section 3 by Pexels on Pixabay; Section 4 by RDNE Stock project on Pexels; Section 5 by ZigmarsBerzins on Pixabay; Section 6 by Pexels on Pixabay; Section 7 by Juliano Astc on Pexels.