Pharmacy MCA Debt: The PBM Reimbursement Trap
Independent pharmacies are stacking MCA debt to cover PBM reimbursement delays. Here's why it happens and how to fix it without another advance.
The Prescription You Filled Three Weeks Ago Still Isn't Paid For
You filled it, you billed it, the patient walked out with their medication — and now you’re waiting. Thirty days. Forty-five. Sometimes longer, depending on the plan. That’s the reality of running an independent pharmacy today: you front the cost of the drug, the pharmacy benefit manager (PBM) adjudicates the claim, and the actual cash doesn’t land in your account until weeks later, often at a reimbursement rate that barely covers what you paid the wholesaler in the first place.
Meanwhile, rent is due on the first. Payroll runs every two weeks. Your wholesaler wants payment on terms that don’t care what your PBM remittance schedule looks like. So when a broker calls with same-day funding and no waiting period, it’s easy to see why so many independent pharmacy owners say yes — and why, twelve or eighteen months later, so many of them are juggling three, four, even five merchant cash advances against the same thin margin.
If that’s where you are right now, here’s what matters most: this is fixable, and it doesn’t require signing up for another advance to buy time on the last one. Let’s walk through why pharmacies get stacked so fast, what’s actually in those contracts, and what real options exist to get your cash flow back under your control.
Why PBM Reimbursement Timing Makes Pharmacies an MCA Target
Pharmacy economics are unlike almost any other small business. You’re extending credit to insurance companies every single day, whether you realize it or not. The drug goes out the door immediately; the money comes back on the PBM’s schedule, not yours. Add in DIR (direct and indirect remuneration) fee clawbacks that can arrive months after a claim was originally adjudicated, and an independent pharmacy can look profitable on paper while sitting on a genuine cash gap in the bank.
MCA funders know this pattern well, and they underwrite around it. A pharmacy’s daily card and insurance receivables volume can look strong enough to qualify for a large advance quickly — often within 24 to 48 hours, with minimal documentation. The Federal Reserve’s Small Business Credit Survey has consistently found that owners with urgent cash needs are far more likely to accept the first fast financing offer they receive, rather than shopping multiple options — and MCA companies are built to be that fast offer.
The problem is that one advance rarely solves a timing mismatch that’s structural, not temporary. If PBM reimbursement is running 30 to 60 days behind your outgoing costs every single cycle, a 4- to 6-month MCA term with a daily debit doesn’t close that gap — it just adds a new, faster-draining obligation on top of the old one. That’s the mechanism behind stacking: each advance is taken to cover the hole the last one’s daily debit created.
The Math Most Owners Don't See Until It's Already a Problem
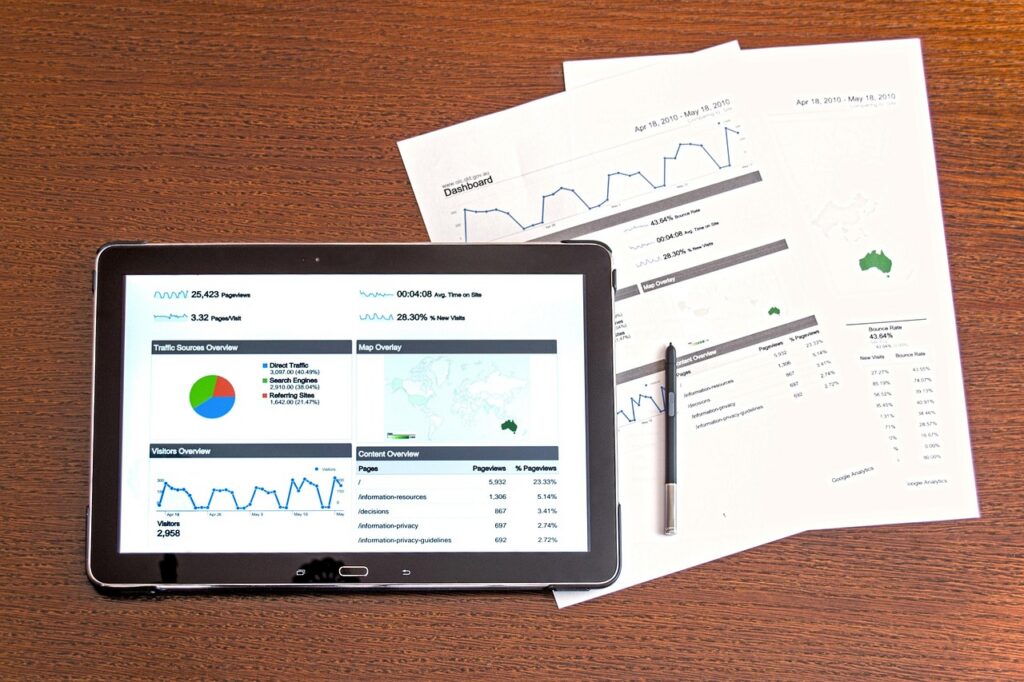
An MCA isn’t a loan with an interest rate — it’s a purchase of a percentage of your future receivables, priced with a factor rate. A $60,000 advance at a 1.35 factor means you owe $81,000 back, typically collected through a fixed daily ACH debit or a percentage holdback on card and claim revenue, regardless of whether that particular day was slow. For a pharmacy already waiting on PBM money, a fixed daily debit doesn’t pause because a big reimbursement batch hasn’t cleared yet.
Most MCA contracts also include a reconciliation clause — language that’s supposed to let you adjust the debit amount if revenue drops. In practice, funders often require extensive documentation and can deny or delay reconciliation requests, leaving the fixed debit running while you fight for an adjustment. Many owners don’t realize reconciliation is even negotiable until they’re several advances deep.
Then there’s the lien question. Most MCA agreements include a UCC-1 filing against your business receivables — a public notice that the funder has a claim on money coming in. Stack three or four of these against the same pharmacy and you can end up with competing liens, each funder aware that others are also pulling from the same daily deposits, which is exactly the dynamic that pushes funders to escalate collection fast if a payment is missed.
Personal Guarantees, Confessions of Judgment, and What's Actually Enforceable
Nearly every MCA contract carries a personal guarantee, meaning the funder can pursue your personal assets — not just the pharmacy’s — if the business defaults. Some contracts still include a confession of judgment (COJ), a clause where you pre-agree to a judgment against you without a court hearing if you fall behind. New York banned COJs against out-of-state small businesses in 2019 after widespread abuse documented by the New York Attorney General’s office, but COJs can still appear in contracts governed by other states’ law, so it matters where your agreement says disputes will be decided.
Regulators have taken real action in this space. The Federal Trade Commission has brought enforcement actions against MCA companies over deceptive advance terms and abusive collection tactics, and the Consumer Financial Protection Bureau has published data on the small-business financing gaps that drive owners toward high-cost alternative funding in the first place. None of this means every funder acts in bad faith — many operate within the rules — but it does mean the contracts deserve real scrutiny before you sign, and real leverage exists if you’re already in one.
A handful of states, including New York, California, and Virginia, now require commercial financing disclosures similar to an APR, making the true cost of an advance easier to see up front. If you’re evaluating a new offer, checking whether your state has adopted one of these disclosure laws is worth five minutes before you sign anything.
A Composite Case: Four Funders, One Reimbursement Cycle
Consider a composite scenario built from patterns we see repeatedly across independent pharmacies: an owner takes a first advance to cover a slow reimbursement quarter, then a second to cover the first advance’s daily debit six months later, then a third and fourth as PBM DIR fee clawbacks hit unexpectedly. Within two years, the pharmacy is carrying four active advances against the same receivables stream, with combined daily debits eating nearly a third of gross revenue before a single bill gets paid.
In cases like this, a negotiated resolution across all four funders at once — rather than trying to settle one at a time while the others keep debiting — is typically the fastest way to restore cash flow. In past settlements built on this kind of stack, we’ve seen combined balances in the $150,000 to $250,000 range resolved for 65% to 80% below the total amount owed, freeing up daily cash flow within weeks instead of the months it would take negotiating funder by funder.
This is a composite illustration, not a specific client, and every pharmacy’s situation is different — the funders involved, the state law governing the contracts, and how far into default the debt already is all change what’s realistically achievable. Results vary and are not guaranteed. But the pattern itself, and the negotiated outcomes, reflect what’s actually possible when a stack gets addressed as one coordinated resolution instead of five separate fires.
What Actually Happens When PBM Cash Finally Catches Up — And You're Already Stacked
Here’s the frustrating part for a lot of pharmacy owners: the PBM money does eventually come in. The reimbursement lands, the DIR fee reconciliation clears, and for a moment the bank balance looks healthy — right before three or four daily debits pull it back down to nothing. Owners describe it as running the pharmacy purely to feed the advances, with no cushion left for inventory restocking, equipment, or an unexpected slow month.
This is the point where most owners start looking for a way out, and there are real ones. A hardship request asks a funder directly to pause or reduce debits for a defined period — funders will sometimes agree, particularly if you can show documentation of the PBM payment cycle causing the mismatch. A structured settlement plan restructures the total owed into a longer, lower payment that actually fits your real cash flow instead of a factor-rate schedule built for a different kind of business. In cases with multiple stacked funders, a negotiated resolution across all of them at once — sometimes for a lump sum well below the combined payoff amount — can end the daily-debit bleeding in a matter of weeks rather than months.
For pharmacies carrying an especially heavy stack, Subchapter V of the Bankruptcy Code, a streamlined reorganization option for small businesses created by Congress and explained in detail by the federal courts, can also be worth evaluating with a business attorney — particularly when receivables are already tied up in competing UCC liens from multiple funders.
You Don't Have to Take Out a Sixth Advance to Fix This
If you’re an independent pharmacy owner reading this because the daily debit just hit and the PBM reimbursement still hasn’t landed, take a breath — you are far from the only pharmacy in this exact position, and it is genuinely solvable. The instinct to take one more advance to bridge the gap is understandable, but it’s almost always the move that turns a hard month into a multi-year problem. There’s a difference between buying time and buying trouble.
We’ve seen stacked pharmacy balances resolved through negotiated settlement at 60%, 70%, even 80% below the combined payoff owed across multiple funders. Results vary and are not guaranteed — every situation depends on the specific funders, contract terms, and how far along the debt already is — but structured negotiation, hardship requests, and lump-sum settlements are real tools that funders engage with regularly, not theoretical options.
The right first step isn’t another application for capital. It’s an honest look at every contract you’re currently in, and a conversation with someone who negotiates these resolutions for a living. Speak with an MCA Relief Specialist or a business attorney about your specific stack before your next debit hits — this is general information about commercial business debt, not consumer debt advice, and every pharmacy’s situation is different enough that it deserves a real conversation, not a guess.
Photo credits: Featured image by cottonbro studio on Pexels; Section 1 by Navy Medicine on Unsplash; Section 2 by Vitaly Gariev on Unsplash; Section 3 by Pexels on Pixabay; Section 4 by Vagaro on Unsplash; Section 5 by Vitaly Gariev on Unsplash; Section 6 by Zulfugar Karimov on Unsplash; Section 7 by stevepb on Pixabay.